Loading…
Loading…
Also serving Trichur
Thrissur has been lending against gold and running kuries for generations; the firms that grow from here need loan software that posts every receipt to a real ledger.
Official ERPNext Partner · 100+ ERP projects · Since 2011
Or call +91 62358 66111
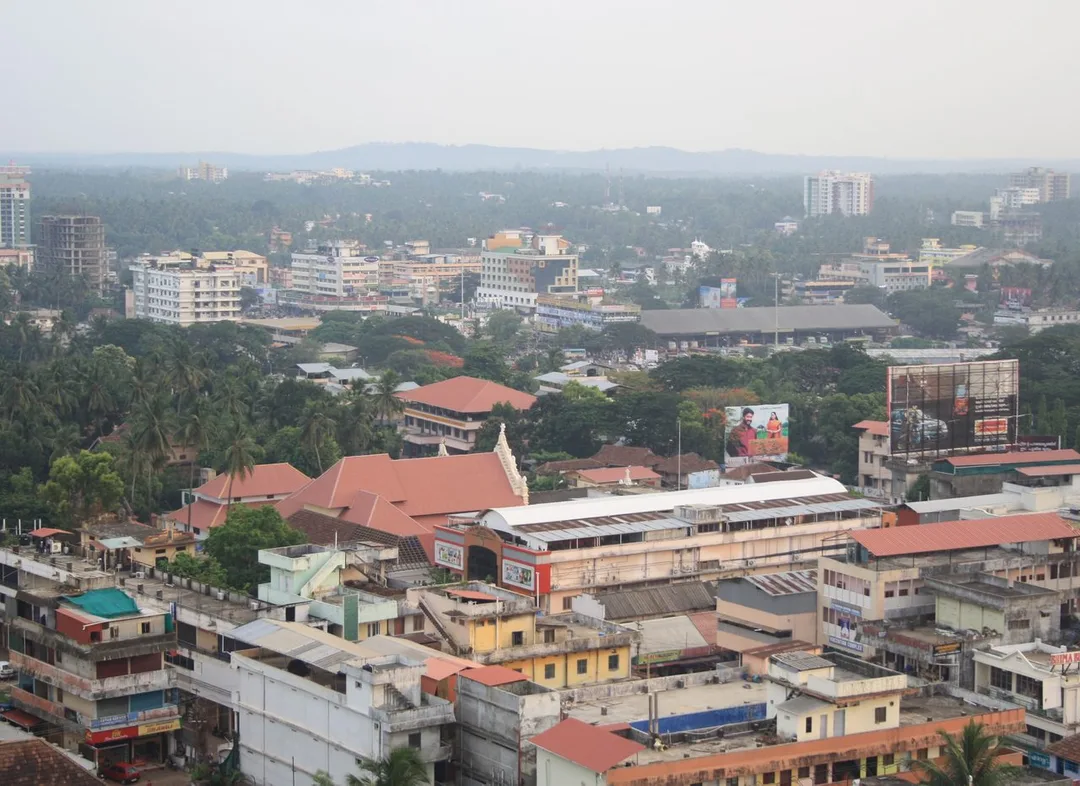
Photo: Jpullokaran · CC BY-SA 3.0, cropped · via Wikimedia Commons
Trusted by 200+ organisations across India & overseas — including
An example
At a gold loan branch in Kunnamkulam on a Tuesday, a printing-press worker brings in a chain and two bangles. The officer weighs them, records weight, purity and the day's valuation against a new application, photographs the ornaments, and prints the packet label from the same screen. The sanction is within his branch limit, so the maker-checker approval comes from the assistant beside him and the disbursal is paid out and posted to the ledger in the same movement. Meanwhile a field agent is collecting instalments on a route through Irinjalakuda; each receipt is recorded at the door on his phone, and the branch manager watches the day's collection build without a phone call. At head office in Thrissur the overdue ageing for this branch updates as the receipts land, and the month's NPA report will need nobody to type anything.
Few towns in India have as deep a lending tradition as Thrissur. Banks, non-banking finance companies, gold loan firms, kuri companies and service co-operative societies are headquartered or rooted here, with offices in Sakthan Thampuran Nagar and branches in every municipality from Kunnamkulam to Irinjalakuda. They share a growth path: a loan book that starts in a bound register, moves to a locally built desktop program, and outgrows it when branches multiply and the regulator asks for reports the program cannot produce.
Our loan and lending management software is built on ERPNext. It covers loan products, application and KYC, sanction workflows, disbursal, repayment schedules, interest and penalty accrual, security and collateral, field collection on mobile, and overdue and NPA reporting. Because it sits on a full accounting system, every transaction reaches the general ledger by itself.
Case studies
Adventure Sports Cover 360 (ASC360)
ASC360 — ERPNext + Mobile App Cut Policy Issuance Time 70%
MultiWealth Capital
MultiWealth Capital — ERPNext Cut Loan Processing Time by 60%
Dumas Bakes N Meals Private Limited
Dumas Bakes N Meals — ERPNext Lifted On-Time Deliveries by Over 40%
When the loan program and the accounting package are separate, someone posts daily totals by journal and the two drift apart. On a single platform, a disbursal or a repayment is one entry that updates the borrower's account and the ledger together, and the trial balance always ties to the loan book.
Details of pledged ornaments are written on the packet and in a register, and an audit means opening the vault and reading labels. Recording each pledge with weight, purity, valuation and packet number against the loan gives the auditor a list to verify and the branch a clear release procedure.
Field agents collect in cash and report in the evening. A mobile collection screen records each payment at the customer's door with location and receipt, so the branch manager sees collections as they happen and knows which visits were missed.
Lending implementations begin with your product sheet and your sanction policy. We sit with your operations and accounts heads in Thrissur to configure each product exactly as you lend it, then migrate the live loan book with balances verified account by account on a sample and in total. Branches go live in groups. Our Kochi support desk stays close through the first month-end and the first audit.
Discovery. Your loan products, interest methods, collection routine and reporting.
Blueprint and fixed scope. A clear plan, the deliverables and the timeline, agreed in writing before configuration starts.
Configuration. Loan products, schedules, disbursement, repayment, collections and the books behind them.
Data migration. Borrowers and running loans with their schedules and outstanding balances.
Training, go-live and support. Your team tests on real data, we stand beside you at launch, then support continues under a plan.
The scope and timeline are agreed in writing before work starts.
Banking and financial services
Configurable gold, business and personal loan products, branch-wise sanction limits with maker-checker approval, automated interest and penal charges, overdue ageing and NPA classification, and portfolio reports for the board and for funding banks.
Gold and jewellery manufacturing and retail
For jewellery groups with a finance arm, pledge records that carry ornament weight and purity, valuation against the day's rate, renewal and auction workflows for defaulted pledges, and a clean separation between the showroom's books and the lender's.
Timber, plywood and furniture
For furniture and home-goods dealers who sell on instalments, a simple loan product per sale, repayment schedules with reminders, receipts at the counter or by agent, and overdue lists that show who to call this week.
The standard product is a lending system. Kuri operations, with subscriptions, auctions, prize money and foreman's commission, need additional customisation, which we scope separately. Many Trichur firms run both, so we design the two to share customers and accounts where that makes sense.
It produces ageing, NPA classification, provisioning, interest accrual and portfolio reports as standard. Formats required by a specific regulator or lender are built as custom reports on the same data. We review your reporting obligations during scoping so nothing is discovered after go-live.
Customers, active loans, schedules, outstanding balances and pledge details are extracted from your present system, loaded in a test environment, and reconciled with your books. Only when totals and a checked sample agree do we repeat the load for the live cutover.
After a first conversation about your loan products, branches and the volume of running loans, we agree the scope and send you a written quotation. The price, the deliverables and the timeline are fixed against that scope before any work starts, so nothing grows without your sign-off.
You speak to someone who does this work, not a call centre. They ask about your loan products, how collections run and what you use today. If it looks like a fit, we agree the scope and put it in writing, with the timeline, before any work starts. If it does not, we tell you.
Sakthan Thampuran Nagar, Thrissurmarket
business district with the city vegetable and fish markets, a major bus stand and bank and company offices
The head offices of banks and finance companies in this business district are where branch loan books are consolidated, audited and reported to boards and funding banks.
Source: en.wikipedia.orgIrinjalakuda Municipalitylocal body
A typical branch town for Thrissur lenders, where field agents collect on foot and a mobile receipt at the door replaces the evening cash count.
Kunnamkulam Municipalitylocal body
Printing workers and small traders here form a steady gold-loan and instalment clientele, and a branch running within its own sanction limit still has to post every entry to the head-office ledger.
Places and organisations are named for local context only. Acube Innovations is not affiliated with or endorsed by them.
Get a clear plan, an honest timeline, and a fixed scope. Talk to a real expert today — whether or not you work with us.
or write to info@acube.co
Kochi (Kadavanthra & Infopark) · Thiruvananthapuram · across India & overseas · In business since 2011